Filing Alert: Mercer International Chapter 11
Mercer International Inc., a Vancouver, BC-based global forest products company engaged in the manufacture and sale of market pulp, lumber, mass timber produ...
Mercer International Inc. and its debtor affiliate⁽¹⁾, a Vancouver, BC-based global forest products company engaged in the manufacture and sale of market pulp, lumber, mass timber products, pallets, biofuels, electricity, and chemicals, filed for Chapter 11 protection on Nov. 9 in the U.S. Bankruptcy Court for the Southern District of Texas.
The company attributes its distress to near-term debt maturities, an expansion funded partly with new debt, weak pulp markets, rising fiber and energy costs, adverse currency movements, and geopolitical and trade uncertainty. Between 2017 and 2023, the company made acquisitions totaling approximately $803 million, funded primarily with additional debt and available cash. Operating EBITDA fell from approximately $243.7 million in 2024 to negative $22.2 million in 2025. The Canadian ABL facility and German RCF at its non-debtor operating subsidiaries mature in January and September 2027, respectively, and talks with those lenders did not produce an extension or refinancing on commercially viable terms. While negotiating with an ad hoc group of senior noteholders, the company elected not to make an approximately $25.8 million Oct. 1 interest payment on its 2028 senior notes. On Nov. 2, it entered into RSAs with holders of approximately 87.25% of the senior notes and with certain equity holders.
Only the holding company level is in Chapter 11. The business operates through non-debtor affiliates, and all of the company's secured debt sits at those subsidiaries and is left unimpaired. The "straddle" prepackaged plan would cut total funded debt from approximately $1.6 billion to approximately $700 million and reduce annual cash interest expense by approximately $100 million. The approximately $1.3 billion of senior notes would be cancelled. In exchange, holders would receive 91.5% of the new common stock (subject to dilution), 56.5% of the new convertible preferred stock, and $150 million of takeback senior secured notes. They would also receive subscription rights in a fully backstopped rights offering of up to $420 million of new money senior secured notes, providing up to $400 million of new liquidity, with participants also receiving stapled equity of 40.0% of the new common stock and 40.0% of the new convertible preferred stock. Existing equity would receive 8.5% of the new common stock (subject to dilution) and 3.5% of the new convertible preferred stock. Proceeds from the rights offering and a new ABL facility of up to $300 million would reduce Canadian ABL borrowings, repay the German RCF in full, and fund post-emergence liquidity.
The debtors intend to fund the cases with unencumbered cash, without DIP financing or use of cash collateral. General unsecured claims, including trade claims, would be unimpaired, and the company targets emergence by Dec. 31, 2026, subject to domestic and foreign regulatory approvals.
The company reports $1.9 billion in assets and $2 billion in liabilities. The filing indicates that there will be funds available for distribution to unsecured creditors. The case number is 26-90829.
⁽¹⁾ Mercer International (Texas) LLC.
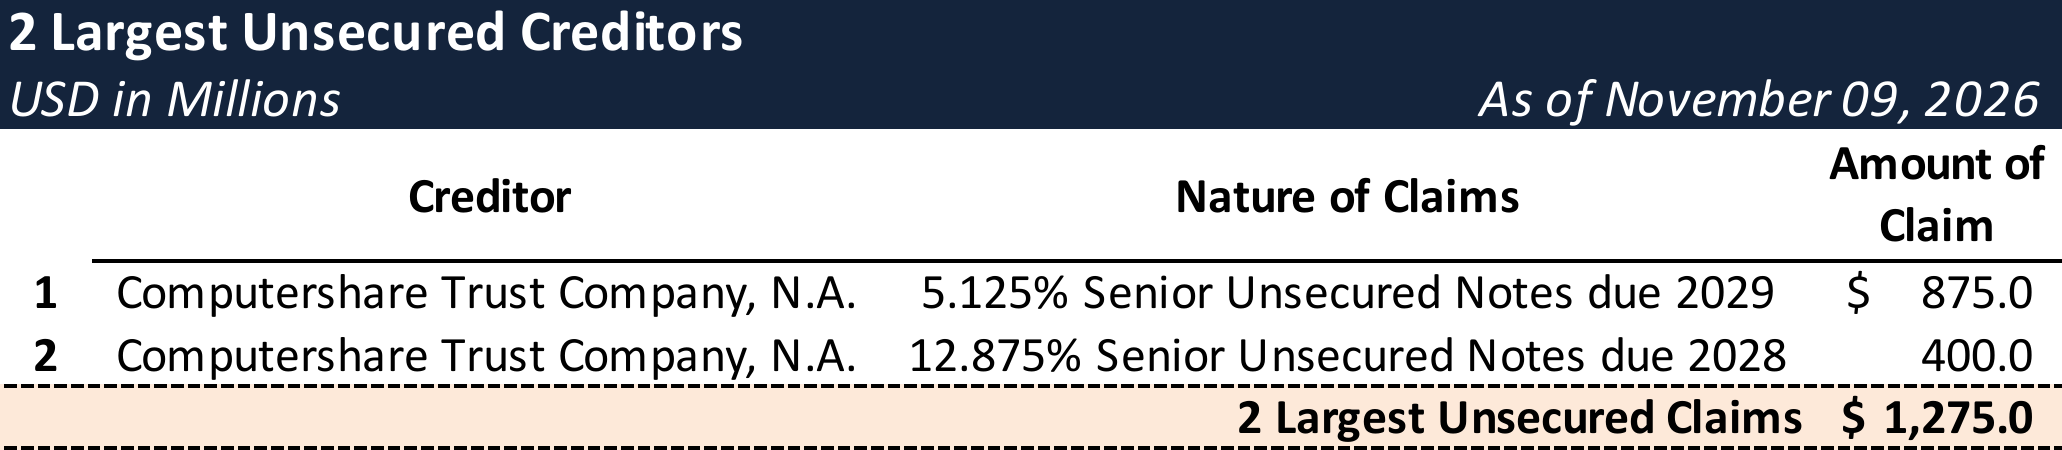
Top Unsecured Claims
Key Parties
Counsel:
- Timothy A. (“Tad”) Davidson II
Hunton Andrews Kurth LLP
Email: taddavidson@Hunton.com
Counsel:
- Latham & Watkins LLP
Financial Advisor:
- Alvarez & Marsal North America, LLC
Investment Banker:
- Houlihan Lokey Capital, Inc.
Signatories:
- Richard Short – Chief Financial Officer
Claims Agent:
- Stretto, Inc.
Equity Security Holders:
- Peter R. Kellogg – 5% or More of Voting Securities
- Goose Creek Capital, Inc. – 9.40% Equity Interest
- IAT Reinsurance Company Ltd. – 8.51% Equity Interest